

Blogs
PW Consulting: Chemical Catalyst Market to Reach $511.9 Million by 2032, Growing at 4.48% CAGR
By PW Consulting, 2026-09-16
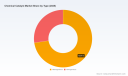
Strategic Imperatives in the Global Chemical Catalyst Market: A 2026 Outlook
The chemical catalyst market stands at a critical inflection point in 2026. As industries navigate the dual pressures of decarbonization mandates and supply chain volatility, catalysts have evolved from mere process enablers to strategic assets that dictate operational efficiency, regulatory compliance, and long-term competitiveness. For executives steering portfolio strategy, capital allocation, and R&D roadmaps, understanding the trajectory of this market is no longer optional—it is foundational.
Precious Metal Catalyst Market
Our latest comprehensive market research report on the chemical catalyst sector provides executives with a rigorous, data-grounded framework to navigate the coming years. Spanning historical performance from 2020 through 2025 and projecting forward to 2032, this analysis captures the structural shifts, competitive maneuvers, and demand-side transformations that will define the industry landscape. Below, we preview the strategic dimensions of this research and articulate why it constitutes an indispensable decision-support tool for 2026 and beyond.
The Macro Trajectory: Sustained Growth Anchored in Industrial Demand
The global chemical catalyst market has demonstrated remarkable resilience and expansion over the past half-decade. Valued at approximately 298.15 million USD in 2020, the sector climbed steadily to reach 375.4 million USD by 2025. This upward trajectory reflects the compounding effect of industrial digitization, expanding petrochemical capacity in emerging economies, and the accelerating deployment of catalysts in environmental and sustainability-driven applications.
Chemical Catalyst Market
Looking ahead, the market is projected to maintain a compound annual growth rate of 4.48 percent through 2032, translating into a valuation of roughly 511.9 million USD by the end of the forecast horizon. This growth is not uniform; it is being shaped by divergent regional industrialization rates, shifting feedstock economics, and deliberate capacity investments by leading manufacturers. For corporate strategists, the implication is clear: the next seven years will reward organizations that align their catalyst procurement, R&D partnerships, and geographic exposure with the underlying demand vectors rather than reacting to short-term price fluctuations.
The report provides a granular breakdown of how these growth dynamics unfold across heterogeneous and homogeneous catalyst categories, as well as across application verticals ranging from petrochemical processing to polymerization, chemical synthesis, and environmental remediation. Rather than presenting static market shares, the analysis maps the interaction between technology readiness, regulatory timelines, and end-user procurement cycles—offering a dynamic view of where value creation is concentrating and where margin compression looms.
Structural Shifts Shaping the 2026 Competitive Landscape
The catalyst industry in 2026 is characterized by a blend of maturity and disruption. On one hand, the market exhibits moderate concentration, with the top three players accounting for approximately 35.5 percent of revenue and the top five commanding 42.0 percent. This concentration reflects the high barriers to entry associated with catalyst development, including proprietary formulation expertise, stringent performance validation, and long qualification cycles in downstream industries. On the other hand, the landscape is being reshaped by technological breakthroughs, evolving environmental regulations, and raw material cost volatility that are altering competitive moats.
Technology and Material Innovation as Differentiators
Recent product launches and capacity expansions underscore how leading firms are leveraging innovation to defend and expand their positions. BASF SE has been particularly active, inaugurating the world's first production facility for 3D-printed sulfuric acid catalysts—a development that signals a broader industry pivot toward advanced manufacturing techniques that enable customized catalyst geometries, improved mass transfer, and reduced waste. Concurrently, the German giant has opened a state-of-the-art R&D center for refinery catalysts co-located with its largest global production site, reinforcing the strategic linkage between research velocity and manufacturing scale. Earlier innovations, such as the SYNSPIRE G1-110 catalyst deployed at Nan Ya Plastics' 2-EH plant, have already demonstrated measurable operational benefits, including annual steam savings and significant CO2 reductions, highlighting how catalyst performance directly translates into sustainability metrics that matter to both regulators and end customers.
Clariant AG has similarly pursued a sustainability-forward product strategy, introducing titanium-based AddWorks catalyst solutions for polyester polymerization as a greener alternative to traditional antimony catalysts. This launch, alongside the earlier deployment of MegaMax 900 methanol synthesis catalysts at European Energy's e-methanol facility in Denmark, illustrates a broader industry trend: catalysts are increasingly being engineered not only for reactivity and selectivity but also for reduced toxicity, lower environmental footprints, and compatibility with renewable feedstock pathways.
Regulatory Pressures and Compliance as Strategic Filters
Regulatory frameworks are exerting an ever-stronger influence on catalyst development, procurement, and market access. Catalyst manufacturers operating in or exporting to European markets must comply with REACH regulations governing substance registration, safety data sheet preparation, and exposure monitoring. For global buyers and suppliers alike, these requirements introduce additional layers of due diligence, documentation, and lifecycle management. Companies that have invested early in compliant formulations, transparent supply chain tracing, and integrated safety protocols are positioned to shorten qualification timelines and reduce regulatory friction. Those lagging behind face the risk of market exclusion or costly remediation. The report examines how REACH compliance and analogous regulatory regimes in other jurisdictions are shaping product portfolios, R&D priorities, and regional market entry strategies.
Feedstock Economics and Raw Material Dynamics
Raw material cost volatility represents another critical variable for 2026 planning. Sulfuric acid, a foundational catalyst precursor and process chemical, has experienced notable price movements driven by shifts in elemental sulfur availability and broader commodity market dynamics. In April 2026, sulfuric acid prices reached approximately 280.80 USD per metric ton in China and 367.80 USD per metric ton in the United States, with upward pressure stemming from reduced byproduct output from copper and zinc smelting operations and volatility in crude oil markets that influence refining activity. For catalyst producers, these feedstock cost fluctuations directly affect margin structures and pricing strategies. For downstream users, they introduce uncertainty into total cost of ownership calculations and underscore the importance of long-term supply agreements, alternative feedstock strategies, and catalyst formulations that optimize material efficiency.
Competitive Intelligence: Navigating a Crowded and Evolving Field
The chemical catalyst market features a diverse set of global players, each with distinct technological competencies, geographic footprints, and strategic priorities. BASF SE, headquartered in Ludwigshafen, Germany, remains a dominant force, particularly in sulfuric acid catalysts, FCC catalysts, and industrial adsorbents. Its recent capacity expansions and R&D investments signal a clear commitment to securing leadership in both traditional and next-generation catalyst applications. Johnson Matthey PLC, based in London, continues to leverage its expertise in precious metal and PGM catalysts to serve chemical and petrochemical end markets, with a particular strength in high-value, performance-critical applications.
Clariant AG, from its Muttenz, Switzerland base, has carved out a strong position in catalysts for propylene, ethylene, and syngas processes, while increasingly differentiating through sustainable formulations. W.R. Grace & Co., operating from Columbia, Maryland, maintains a focused presence in FCC and hydroprocessing catalysts for refining and petrochemical industries, where process reliability and catalyst longevity are paramount. Albemarle Corporation, headquartered in Charlotte, North Carolina, brings its refining and petrochemical catalyst expertise—including its well-known Ketjen brand solutions—to a competitive field where incremental performance gains can yield substantial operational savings.
Haldor Topsoe A/S, based in Lyngby, Denmark, specializes in hydroprocessing and syngas catalysts for chemical synthesis, positioning itself at the intersection of traditional refining and emerging energy transition pathways. Umicore SA, from Brussels, Belgium, brings deep expertise in automotive and industrial precious metal catalysts, leveraging its materials science capabilities across multiple verticals. Evonik Industries AG, headquartered in Essen, Germany, develops specialty catalysts and adsorbents that address niche but high-value chemical applications, often in partnership with downstream innovators. Axens, from Rueil-Malmaison, France, provides catalyst technologies tailored to oil refining and petrochemical processes, with an emphasis on integrated solution delivery. Finally, Sinopec Catalyst Co., Ltd., based in Beijing, China, stands as a major producer of refinery and petrochemical catalysts, reflecting the broader rise of Chinese manufacturers in global supply chains and their increasing capability in both volume production and technology development.
The report provides detailed profiles of these and other key players, analyzing their strategic moves, capacity investments, product launches, and partnership ecosystems. By mapping competitive dynamics against market segmentation and regional demand patterns, the analysis equips executives with the intelligence needed to anticipate competitor behavior, identify partnership opportunities, and assess threats to existing supplier relationships.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Makers
Beyond macro trends and competitive snapshots, this market research report is structured to support concrete business decisions across multiple functional areas. The following elements represent the core operational value provided to subscribers:
- Segmentation Analysis Across Type and Application: The report dissects the market by heterogeneous and homogeneous catalyst types, as well as by application verticals including petrochemicals, polymerization, chemical synthesis, and environmental uses. Each segment is evaluated through the lens of growth drivers, technology maturity, pricing dynamics, and end-user procurement behavior, enabling readers to identify high-opportunity niches and assess the strategic fit of their product or procurement portfolios.
- Regional Demand Mapping and Trade Flow Insights: While the global market is projected to grow steadily, regional trajectories diverge significantly based on industrialization pace, regulatory environment, feedstock availability, and local manufacturing capacity. The analysis provides a nuanced view of demand concentration and growth momentum across key geographies, helping executives calibrate market entry strategies, supply chain configurations, and investment prioritization.
- Competitive Landscape and Strategic Group Mapping: Detailed assessments of leading companies—including their technological capabilities, recent developments, and strategic positioning—allow readers to benchmark their own organizations, identify potential collaborators or acquisition targets, and anticipate shifts in market share and pricing power. The report's coverage of recent capacity expansions, product launches, and R&D investments provides a real-time window into how competitors are shaping the future market structure.
- Regulatory and Compliance Roadmap: With REACH and analogous regulations increasingly influencing catalyst development and market access, the report offers a structured overview of compliance requirements, documentation expectations, and best practices for managing regulatory risk across jurisdictions. This section is designed to support procurement, legal, and R&D teams in aligning their processes with evolving standards.
- Raw Material and Feedstock Risk Assessment: Given the sensitivity of catalyst economics to raw material costs—particularly elemental sulfur, precious metals, and specialty precursors—the report includes an analysis of price trends, supply constraints, and mitigation strategies. This intelligence supports procurement planning, cost modeling, and supplier negotiation strategies in an environment of persistent commodity volatility.
- Forecast Scenarios and Strategic Planning Tools: The 2026–2032 forecast framework is built to support scenario planning, allowing readers to test assumptions around growth rates, segment shifts, and regional demand under different macroeconomic, regulatory, and technology adoption pathways. This flexible structure ensures that the analysis remains relevant even as external conditions evolve.
Strategic Value for 2026 Executive Decision-Making
In an environment where catalyst performance directly influences process efficiency, emissions profiles, and total operating costs, the ability to anticipate market shifts is a decisive competitive advantage. The insights contained in this report are designed to support decision-making across several critical dimensions:
- Portfolio Strategy and R&D Prioritization: By identifying which catalyst types and application segments are experiencing the strongest demand momentum and technological innovation, executives can align R&D budgets, partnership investments, and product development roadmaps with the highest-value opportunities. The analysis of recent product launches and capacity expansions provides a concrete reference point for evaluating where the industry is heading and where white space may exist.
- Procurement and Supply Chain Optimization: For downstream users and industrial buyers, the report's segmentation and regional analysis supports more informed supplier selection, contract structuring, and inventory strategies. Understanding where supply is concentrated, which technologies are gaining traction, and how raw material costs are evolving enables procurement teams to negotiate from a position of knowledge rather than reacting to spot market fluctuations.
- M&A and Partnership Evaluation: The competitive landscape section, combined with the market concentration data and segment growth profiles, provides a structured basis for evaluating potential acquisitions, joint ventures, or technology licensing arrangements. Executives can assess which capabilities are most strategically valuable, which players are strengthening their positions, and where consolidation dynamics may create openings.
- Risk Management and Regulatory Preparedness: With REACH compliance, feedstock volatility, and sustainability expectations all exerting pressure on catalyst markets, the report's coverage of regulatory requirements, raw material trends, and compliance best practices helps organizations anticipate disruptions and build resilience into their operations and supplier relationships.
- Capital Allocation and Geographic Strategy: The regional and segment forecasts support more disciplined capital allocation decisions, whether for new production capacity, R&D facilities, sales and distribution investments, or market entry initiatives. By understanding where demand is growing and which regions present the most favorable regulatory and economic conditions, executives can prioritize investments with greater confidence.
Conclusion: Turning Market Intelligence into Strategic Advantage
The chemical catalyst market is entering a phase where technological innovation, regulatory evolution, and raw material dynamics will increasingly determine which companies capture value and which face margin erosion or strategic obsolescence. The data presented in this research—spanning historical performance, current competitive dynamics, and forward-looking forecasts through 2032—provides a comprehensive foundation for navigating this complexity.
The trajectory from 375.4 million USD in 2025 to an estimated 511.9 million USD by 2032, supported by a 4.48 percent CAGR, reflects more than aggregate growth. It reflects a market being reshaped by deliberate investments in advanced manufacturing, sustainable catalyst formulations, and integrated solution delivery. Companies that understand these shifts at a granular level will be better positioned to optimize procurement, direct R&D investments, manage regulatory risk, and forge strategic partnerships that compound advantage over time.
This report is designed to serve as a strategic reference point for executives across the chemical, petrochemical, refining, environmental, and advanced materials sectors. It combines rigorous quantitative analysis with qualitative insights into competitor behavior, technology trends, and regulatory developments, all structured to support actionable decision-making in 2026 and the years ahead.
To access the full segmentation breakdowns, detailed company profiles, regional demand maps, regulatory compliance frameworks, and scenario-based forecasts, we invite you to visit the source page and explore the complete research deliverables. The depth of intelligence contained in the full report is built to support precise, confident decisions in a market where foresight is the ultimate differentiator.
For detailed analysis of this topic, please visit the official page: Chemical Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
China’s terminal block market revenue has shown remarkable resilience, rising from USD 1,850 Million in 2020 to an anticipated USD 3,600 Million by 2025. Sustained investments in industrial and infrastructure sectors, coupled with automation adoption and renewal of aging power distribution networks, continue to fuel market growth. The upward trajectory projects a further surge to close to USD 7,250 Million by 2035 as smart factories, renewable energy-driven infrastructure, and intelligent buildings proliferate nationwide. The consistent revenue expansion underscores the enduring need for scalable connectivity solutions in China’s rapidly digitalizing landscape.
Read More - https://bussinessinsights.com/research-report/china-terminal-block-market
Industrial Controls lead the Chinese terminal block market in 2025, representing 30% of application share. Driven by manufacturing digitization, terminal blocks in industrial controls ensure safe, efficient, and scalable connections. Power Supplies (20%) and Building Automation (18%) follow closely, highlighting China’s focus on smart infrastructure and renewable technologies. Telecom Equipment (12%), Lighting (8%), Railways (5%), HVAC Systems (4%), and Others (3%) also contribute to market expansion. The collective demand across diverse application domains reflects the market's underlying strength and the integral role terminal blocks play in China's ongoing industrial and urban transformation.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-terminal-block-market
Frequently Asked Questions
Who are the key players in China Terminal Block Market industry?
The top five players in the China Terminal Block Market are Phoenix Contact, WAGO, Weidmüller, TE Connectivity, and ABB. These companies are recognized for their innovative technology, wide-ranging product portfolios, and strong distribution networks. They play a significant role in developing high-quality, reliable terminal block solutions for industrial and commercial sectors.
What is the China Terminal Block Market growth?
The China Terminal Block Market has experienced robust growth, driven by increased automation, expanding manufacturing sectors, and rising demand for efficient connectivity. For instance, Phoenix Contact reported sales growth in 2023, owing to increased investments in industrial automation and infrastructural upgrades in China.
Which segment accounted for the largest China Terminal Block Market share?
The industrial control & automation segment holds the largest market share in the China Terminal Block Market. This is due to extensive adoption of terminal blocks in industrial automation systems for secure wiring and connectivity, enabling efficient and reliable control of manufacturing processes across China.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Automotive Exterior Trim Market Hits $219 Billion in 2025, Forecast 4.2% CAGR to 2032
By PW Consulting, 2026-09-16
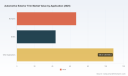
Navigating the Future of Automotive Exterior Trim:2026 Strategic Insights and Market Trajectories
The automotive exterior trim market stands at a critical inflection point in 2026. As vehicle architectures evolve and consumer expectations shift toward enhanced aesthetics, sustainability, and functional integration, manufacturers and suppliers must navigate a landscape defined by both opportunity and volatility. This industry insight draws upon comprehensive market research to outline the strategic imperatives for stakeholders positioning themselves for the 2026-2032 forecast period. Understanding the macro dynamics, competitive pressures, and regulatory tailwinds is no longer optional—it is a prerequisite for capital allocation, product portfolio optimization, and supply chain resilience.
Macro Trajectory and Market Scale
The global automotive exterior trim market has demonstrated consistent expansion over the past half-decade. Historical analysis from 2020 through 2025 reveals a steady climb in total market value, moving from 175.0 billion USD to 219.0 billion USD. This trajectory underscores a market that has not only recovered from earlier supply chain disruptions but has accelerated beyond pre-pandemic benchmarks. Looking forward, the forecast period extending to 2032 projects continued growth, with the market expected to reach approximately 297.0 billion USD by the close of the decade. This expansion is underpinned by a compound annual growth rate of 4.2 percent, reflecting sustained demand across vehicle segments and geographic regions.
Automotive Exterior Trim Market
For enterprise leaders, these figures signal more than top-line growth; they indicate shifting allocation patterns, evolving material preferences, and the increasing importance of localized production strategies. The market's expansion is not uniform across all categories, and understanding where value is concentrating requires a granular view of type, application, and regional dynamics. However, the overarching message is clear: exterior trim is transitioning from a purely cosmetic component to a strategic interface that influences brand identity, aerodynamic performance, and regulatory compliance.
Segmentation Dynamics and Value Distribution
The market structure reveals a diversified ecosystem where multiple material types and application categories coexist. Plastic components command the largest share of the type segmentation, followed by metal and other materials, reflecting the industry's ongoing balancing act between cost efficiency, design flexibility, and weight reduction targets. In terms of application, bumpers and grilles represent significant portions of the market, while other exterior trim applications collectively account for a substantial portion of total revenue. This distribution highlights the breadth of opportunities beyond traditional high-visibility components, as manufacturers increasingly integrate trim elements into lighting housings, wheel arch extensions, and aerodynamic add-ons.
Regional analysis further complicates the picture. Asia Pacific remains the largest revenue contributor, reflecting the scale of vehicle production in the region and the rapid adoption of premium exterior features. North America and Europe follow, each with distinct regulatory environments and consumer preferences that shape demand. Latin America and the Middle East & Africa represent smaller but growing markets, often influenced by import dynamics and localized assembly strategies. The interplay between these regions creates a complex matrix where suppliers must tailor their offerings to meet varying standards for material composition, recyclability, and tariff exposure.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players holding a combined share of approximately 52 percent and the top five capturing around 62 percent. This concentration suggests that scale, technological capability, and long-term OEM relationships provide meaningful barriers to entry. However, the remaining market share is distributed among a diverse set of regional and specialized players, creating ample room for differentiation through innovation, cost engineering, and niche application expertise.
Several industry leaders exemplify the strategies required to thrive in this environment. OPmobility, headquartered in Levallois, France, has expanded its footprint through integrated exterior and lighting solutions, reporting exterior and lighting revenue of 5,312 million EUR in 2025. Its focus on combining functional and aesthetic elements positions it well for vehicles where trim and lighting are increasingly co-designed. Toyoda Gosei Co., Ltd., based in Kiyosu, Aichi, Japan, leverages its polymer expertise and deep automotive heritage to deliver high-quality trim components that meet stringent durability and appearance standards. SMP Deutschland GmbH, located in Bötzingen, Baden-Württemberg, Germany, maintains a strong presence in the European market by emphasizing precision manufacturing and application-specific engineering.
Magna International Inc., from Aurora, Ontario, Canada, brings broad manufacturing scale and systems integration capabilities, enabling it to serve global OEM programs with complex trim assemblies. Flex-N-Gate Corporation, based in Urbana, Illinois, USA, has demonstrated agility in partnership-driven growth, recently supporting SEAT in the launch of the CUPRA Raval, a move that illustrates how trim suppliers can align with brand-specific design narratives. REHAU, headquartered in Rehau, Germany, continues to invest in material science and sustainable polymer solutions, aligning with industry-wide shifts toward recyclability. Polytec Group, from Hörsching, Upper Austria, Austria, and Adler Pelzer Group, based in Hagen, North Rhine-Westphalia, Germany, round out a competitive field that values specialized engineering, regional supply chain resilience, and close collaboration with vehicle manufacturers.
Industry Dynamics Shaping 2026 Decision-Making
Beyond the structural data, several real-time industry developments are reshaping the strategic calculus for 2026. Input costs for exterior trim remain sensitive to raw materials and semiconductor availability, creating cost volatility that requires proactive sourcing strategies and long-term supplier agreements. Tariff dynamics add another layer of complexity; additional tariffs on imported goods have been estimated to increase supplier cost of goods sold by roughly 9 to 12 million USD annually for affected operations. This reality emphasizes the importance of regionalized production, trade-compliant sourcing, and scenario planning around trade policy shifts.
Regulatory frameworks also play a decisive role. USMCA-compliant imports benefit from exemptions within automotive supply chains, providing a competitive advantage to suppliers structured to meet these requirements. This dynamic encourages strategic footprint decisions and partnership models that align with trade agreement criteria. Meanwhile, sustainability is moving from a compliance checkbox to a core design parameter. The SPE Automotive TPO forum in 2025 specifically addressed exterior trim with recycled content materials, signaling that OEMs and tier suppliers are increasingly evaluating trim solutions based on environmental credentials alongside traditional performance metrics.
Recent events further illustrate the pace of change. In February 2026, TMI announced the first winner selected for the 2026 TMI TRIM Road Tour, highlighting ongoing industry engagement around trim innovation and best practices. Earlier, in January 2026, Flex-N-Gate reinforced its market relevance through a partnership supporting SEAT's launch of the CUPRA Raval, demonstrating how strategic collaborations can accelerate product introductions and strengthen brand alignment. These developments, while discrete, reflect broader patterns of collaboration, showcase-driven innovation, and the need for suppliers to maintain visibility across the value chain.
What the Full Study Delivers
To translate these macro trends and competitive signals into actionable strategy, our comprehensive market study provides an in-depth examination of the automotive exterior trim landscape. The research is structured to support executive decision-making across multiple dimensions:
- Detailed market sizing and forecast models that trace revenue evolution from historical baselines through the 2032 horizon, with clear segmentation by type, application, and region.
- Competitive profiling of key players, including capability assessments, strategic focus areas, and recent developments that indicate future positioning.
- Analysis of material and cost dynamics, including raw material exposure, semiconductor dependencies, and tariff impacts on supplier economics.
- Regulatory and trade environment mapping, with particular attention to USMCA compliance, import exemptions, and regional policy shifts that affect supply chain design.
- Sustainability and material innovation tracks, covering recycled content adoption, TPO and polymer advancements, and OEM expectations for environmental performance.
- Application-level insights that go beyond aggregate figures to explore where value is created in bumpers, grilles, and other exterior trim categories.
- Scenario frameworks that help leaders test strategic options against varying assumptions around production volumes, input costs, and regional demand shifts.
This study is designed not merely as a data repository but as a decision-support tool. Each section connects market intelligence to operational implications, enabling teams to evaluate portfolio priorities, identify partnership opportunities, and anticipate structural changes before they become visible in quarterly results.
Automotive Interior Exterior Trim Market
Strategic Imperatives for 2026
As organizations plan their 2026 initiatives, several priorities emerge from the market intelligence. First, supply chain architecture must balance cost efficiency with resilience, particularly in light of tariff exposure and raw material volatility. Regionalized production and trade-compliant sourcing are no longer theoretical advantages; they are practical necessities for protecting margins. Second, material strategy requires continuous re-evaluation. The growing emphasis on recycled content and sustainable polymers means that suppliers must invest in formulation capabilities and validation processes that meet both performance standards and environmental targets.
Third, competitive differentiation will increasingly come from integration and co-design. Exterior trim is no longer a downstream add-on; it is part of a vehicle's aerodynamic, thermal, and aesthetic system. Suppliers that engage early with OEM design teams and offer modular, application-specific solutions will capture more value than those competing solely on price. Fourth, market intelligence must be continuous. The 4.2 percent CAGR and the projected growth to 297.0 billion USD by 2032 reflect a market that rewards foresight. Leaders who monitor segmentation shifts, competitive moves, and regulatory updates in real time will be better positioned to allocate capital and adjust execution plans.
Looking Ahead
The automotive exterior trim market in 2026 is defined by a blend of steady structural growth, intensifying competitive dynamics, and evolving regulatory and sustainability expectations. The data tells a story of expansion, but the real value lies in understanding where that expansion is concentrated, how costs are shifting, and which capabilities will separate winners from followers. Our full market study provides the depth required to move from observation to action, with detailed segmentation analysis, competitive assessments, and scenario-based guidance tailored for 2026 decision-making.
For executives and strategy teams seeking to navigate this landscape with precision, the complete report offers the granular intelligence necessary to shape product roadmaps, optimize supply chain configurations, and identify high-probability opportunities. The insights summarized here represent only the opening frame; the full study delivers the comprehensive intelligence needed to convert market awareness into strategic advantage.
For detailed analysis of this topic, please visit the official page: Automotive Exterior Trim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hardness Testing Machine Market Hits $359.47 Million in 2025, Projects 6.5% CAGR to 2032
By PW Consulting, 2026-09-16
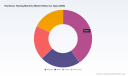
Unlocking Strategic Precision: The 2026 Hardness Testing Machine Market Outlook
In the high-stakes environment of global manufacturing, material integrity is not merely a technical specification; it is the foundation of safety, reliability, and brand reputation. As we navigate through 2026, the Hardness Testing Machine Market stands at a critical inflection point. The transition from traditional manual methods to automated, AI-integrated systems is reshaping how industries validate material properties. For stakeholders, investors, and operational leaders, understanding the trajectory of this market is essential for capitalizing on emerging opportunities and mitigating supply chain risks.
This insight serves as a strategic overview of our comprehensive market research report, designed to equip decision-makers with the intelligence needed to navigate the forecast period of 2026-2032. By analyzing historical trends and projecting future growth, we uncover the underlying forces driving demand and the competitive maneuvers defining the landscape.
Market Trajectory and Growth Dynamics
The global demand for precision testing equipment has demonstrated remarkable resilience and expansion over the past half-decade. Reflecting on the historical performance from 2020 to 2025, the market has evolved from a base of approximately 302.17 million USD to a projected 359.47 million USD in 2025. This steady accumulation of value underscores the indispensability of hardness testing across critical sectors.
Looking ahead, the growth trajectory accelerates. The market is poised to reach 390.32 million USD in 2026, marking a significant step up in valuation. Our forecasts indicate that this momentum will sustain, with the market size expected to surpass the 500 million USD threshold by 2030, eventually reaching 554.71 million USD by 2032. This expansion is driven by an estimated Compound Annual Growth Rate (CAGR) of 6.5 percent throughout the forecast period.
Such growth is not uniform; it is concentrated in specific technological advancements and regional industrial hubs. However, the overarching narrative is one of consistent upscale movement. Companies that align their product development and supply chain strategies with this 6.5 percent growth curve will find themselves better positioned to capture market share as the total addressable market expands.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established global giants and specialized regional players. Analysis of the concentration ratios reveals a fragmented yet competitive environment. The top three players hold a combined market share of approximately 24.6 percent, while the top five control around 26.2 percent. This indicates that no single entity dominates the entire ecosystem, leaving ample room for strategic differentiation and niche targeting.
Key industry leaders are leveraging distinct technological advantages to secure their positions. Buehler, based in Illinois, continues to push the boundaries with Wilson Vickers, Knoop, and Rockwell hardness testers equipped with advanced optical systems and DiaMet software. Their focus on optical precision highlights a trend towards digitizing measurement outcomes. Similarly, ZwickRoell from Germany offers a comprehensive portfolio covering metals, ceramics, plastics, and rubber, emphasizing versatility across material types.
In the North American sector, LECO Corporation and Mitutoyo maintain strong footholds with specialized Rockwell hardness testers, catering to high-volume industrial requirements. Innovation is also evident among European and Asian manufacturers. INNOVATEST in the Netherlands and Struers in the UK provide broad hardness testing solutions, while Chinese manufacturers like Laizhou Huayin Testing Instrument and Beijing Time High Technology focus on Brinell testers and related equipment, often targeting cost-sensitive segments.
Further diversifying the landscape, EMCO-TEST from Austria and Tinius Olsen from the USA contribute with general hardness testers and indentation hardness systems respectively. AFFRI Inc in Italy distinguishes itself with automatic hardness testing machines supporting multiple scales, addressing the need for throughput efficiency. Qualitest, operating out of the United Arab Emirates, offers a vast range of over 100 models spanning Rockwell to Vickers and portable units, highlighting the demand for variety. Foundrax in the UK rounds out the key players with a focus on Brinell hardness testing equipment.
Technological Advancements and Industry Dynamics
The momentum in this sector is heavily influenced by technological integration and regulatory compliance. The industry is witnessing a shift where artificial intelligence begins to revolutionize hardness testing. Recent updates from ZwickRoell in August 2025 highlighted advancements in AI for precision, signaling a move towards smarter, self-calibrating systems that reduce human error.
Portability and on-site capability remain critical drivers. In April 2025, Cisam-Ernst showcased portable hardness testers, including the Computest Lite compact wireless Rockwell hardness tester, emphasizing the need for quick on-site measurements in field conditions. Furthermore, exhibitions such as SAMPE China in June 2026 saw Tinius Olsen showcasing indentation hardness systems and automation solutions, reinforcing the link between testing equipment and broader manufacturing automation trends.
Compliance with international standards acts as both a barrier to entry and a trust signal. ISO standards such as ISO 6506-2:2017 and ISO 6508 specify requirements for both fixed location and portable hardness testing machines. Additionally, ASTM E18-24 Standard Test Methods for Rockwell Hardness of Metallic Materials, published in October 2025, keeps the regulatory framework current. ISO/TC 164/SC 3 continues to standardize indentation testing methods including Brinell, Knoop, Leeb, Rockwell, and Vickers hardness. Adherence to ISO 6508-2:2017 for verification and calibration procedures on various scales ensures that equipment meets rigorous force repeatability and hysteresis requirements. Manufacturers who integrate these standards directly into their product design gain a competitive advantage in regulated industries like aerospace and automotive.
Strategic Implications for 2026 Decision Makers
For executives and strategists, the data points to several actionable insights. First, the growth rate suggests that investment in capacity expansion or R&D for automated testing solutions is timely. Second, the fragmented market concentration implies that partnership or acquisition strategies could yield significant consolidation benefits. Third, the emphasis on standards suggests that compliance certification should be viewed as a marketing asset rather than a mere regulatory hurdle.
However, navigating this landscape requires granular data that goes beyond top-line figures. Understanding the specific revenue contributions of different testing types, the nuanced demand patterns across applications, and the regional intensity of consumption is vital for precise strategic planning. Our full report delves into these specifics, providing a detailed segmentation analysis that breaks down the market by type, application, and region without revealing the sensitive data here.
Hardness Testing Machine Market
Hardness Testing Device Market
Conclusion and Call to Action
The Hardness Testing Machine Market is on a clear upward path, fueled by industrial automation, stricter quality standards, and technological innovation. The window to optimize supply chains and product portfolios according to these trends is open now. To fully leverage the 6.5 percent CAGR and the projected 554.71 million USD market size by 2032, stakeholders need access to the complete intelligence package.
We invite you to explore the full depth of our research. The complete report provides the missing pieces of the puzzle, including detailed segmentation splits by region, type, and application, along with comprehensive company profiles and risk analyses. Equip your organization with the precise data needed to make informed decisions in 2026 and beyond. Access the full market intelligence today to secure your strategic advantage.
For detailed analysis of this topic, please visit the official page: Hardness Testing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China fog computing market is on a formidable growth trajectory. From a revenue base of USD 690 Million in 2020, the market is anticipated to reach USD 1,890 Million in 2025 and soar to USD 11,670 Million by 2035. This surge is underpinned by rapid digitalization, 5G proliferation, and the increasing integration of IoT and AI across industries. The ten-year CAGR stands at an impressive 19.8%. Robust policy support and a collaborative ecosystem of multinational and local players are catalyzing the expansion, positioning China as a global leader in fog-enabled solutions.
Read More - https://bussinessinsights.com/research-report/china-fog-computing-market
Smart manufacturing commands the largest application share in 2025 at 33%, as factories embrace edge-enabled real-time analytics for quality control and automation. Connected healthcare follows with 22% as providers deliver telemedicine and patient monitoring using fog platforms. Smart energy applications account for 16%, reflecting investments in grid optimization and decentralized energy management. Strong growth in transportation & logistics underscores the sector's need for ultra low-latency data processing at the edge. The ongoing digitalization wave ensures that verticals like building automation and logistics will continue increasing their fog computing adoption through the forecast period.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-fog-computing-market
Frequently Asked Questions
Who are the key players in China Fog Computing Market industry?
The leading players in China’s fog computing market include Huawei, Alibaba Cloud, Tencent, China Mobile, and ZTE Corporation. Huawei pioneers in edge computing solutions, Alibaba dominates cloud platform integration, Tencent leverages extensive cloud infrastructure, China Mobile focuses on telecom edge expansion, and ZTE drives IoT-oriented fog deployments.
What is the China Fog Computing Market growth?
The China Fog Computing Market has experienced robust growth, with an annual CAGR of over 18% in recent years. Key growth factors include increasing IoT adoption and strong government digitalization policies. For example, in 2023, Huawei launched advanced fog computing platforms supporting 5G smart city initiatives.
Which segment accounted for the largest China Fog Computing Market share?
The smart manufacturing sector accounted for the largest share of China’s fog computing market. With the adoption of Industry 4.0 standards, manufacturers increasingly deploy fog computing for real-time analytics and automation. Companies like Foxconn have implemented fog-enabled solutions for optimizing operational efficiency and predictive maintenance.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Traditional Whiteboard Market to Reach USD 284 Million by 2032 Amid 3% CAGR
By PW Consulting, 2026-09-16
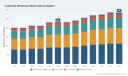
Traditional Whiteboard Market 2026: Strategic Intelligence for the Modern Enterprise
In an era dominated by digital collaboration tools and cloud-based workflows, the physical act of writing, erasing, and visualizing ideas on a traditional whiteboard remains a cornerstone of organizational communication. The Traditional Whiteboard Market has demonstrated remarkable resilience, evolving through material innovations and shifting workplace dynamics while maintaining its foundational role in education, commercial offices, and healthcare environments. As we enter 2026, decision-makers across sectors face a critical need to understand how this legacy market is positioned for sustained growth, competitive pressures, and strategic procurement. This newly released market research provides a comprehensive, data-driven roadmap designed specifically to inform enterprise strategy, supply chain planning, and facility investment decisions for the 2026–2032 horizon.
Why 2026 Demands a Reassessment of Traditional Whiteboard Strategy
The market has navigated a period of consolidation and moderate expansion. Following a compound annual growth rate of approximately 3.0% through the forecast period, revenue trajectories reflect a market that is neither stagnant nor explosively disruptive, but rather steadily maturing with predictable demand cycles. Base-year valuations anchored in 2025 establish a clear benchmark, while historical performance from 2020 through 2025 reveals how supply chain adaptations, educational infrastructure investments, and corporate workspace reconfigurations have collectively shaped consumption patterns. Entering 2026, procurement leaders and strategic planners must look beyond unit-cost considerations and evaluate how material durability, installation flexibility, and end-user workflow integration will dictate long-term value.
Our research deliberately avoids superficial market summaries. Instead, it delivers a structured analytical framework that maps revenue evolution, identifies structural demand drivers, and highlights the operational realities that influence purchasing decisions. By focusing on the interplay between product longevity, environmental conditions, and user behavior, the study equips executives with the context needed to align capital allocation with actual utilization patterns rather than speculative trends.
Navigating a Contained but Competitive Landscape
One of the most defining characteristics of the Traditional Whiteboard Market is its relatively fragmented yet concentrated competitive structure. The top three players collectively command a modest share of total industry revenue, while the top five extend their influence only slightly further. This concentration profile signals a market where regional specialization, product differentiation, and service-level commitments often outweigh pure scale advantages. For enterprises evaluating supplier partnerships or assessing market entry risks, understanding this distribution is essential to constructing resilient sourcing strategies and avoiding overreliance on a narrow supplier base.
Our analysis examines how established manufacturers leverage geographic manufacturing footprints, warranty structures, and application-specific engineering to maintain market positioning. We explore how companies operating across multiple verticals balance standardized production with customized configurations, and how warranty commitments and material certifications influence procurement confidence in institutional settings. The research also maps how competitive intensity varies across product categories, revealing where pricing pressure is most acute and where value-based differentiation remains viable.
Product and Application Realities Shaping Procurement Decisions
Material Choices and End-User Expectations
The market continues to be defined by distinct material categories, each with clear performance trade-offs that directly influence adoption in specific environments. Glass-based surfaces have gained traction in settings where aesthetic finish and long-term write clarity are prioritized. Melamine-based boards remain widely deployed due to their cost efficiency and broad compatibility with standard mounting systems. Porcelain steel surfaces appeal to high-traffic institutional and healthcare environments where surface integrity, chemical resistance, and frequent cleaning cycles are operational necessities. Rather than treating these categories as interchangeable, our research evaluates how each aligns with real-world usage intensity, maintenance expectations, and total cost of ownership considerations.
White Board Market
Where Demand Actually Materializes
Demand is not uniformly distributed across end-use environments. Educational institutions continue to represent the largest consumption base, driven by classroom configuration cycles, replacement schedules, and the pedagogical value of spontaneous visual collaboration. Commercial office environments follow as a substantial secondary demand center, where meeting-room renewal programs, hybrid workspace designs, and collaborative zone planning sustain steady procurement activity. Healthcare settings, while smaller in absolute volume, present specialized requirements around surface hygiene, compliance with cleaning protocols, and durability under rigorous maintenance routines. Our report dissects how these application segments differ in purchasing cadence, specification criteria, and vendor evaluation processes, enabling planners to tailor sourcing approaches rather than applying one-size-fits-all procurement models.
Regional Dynamics and Supply Chain Considerations
Geographic demand patterns reflect broader economic activity, institutional investment cycles, and local manufacturing capabilities. North American markets exhibit strong institutional procurement stability and a mature commercial office refresh environment. European demand is shaped by educational budget frameworks, workplace regulation trends, and a growing emphasis on sustainable product specifications. Asia Pacific presents a distinct profile influenced by rapid educational infrastructure development, expanding corporate real estate portfolios, and localized manufacturing ecosystems. Latin American and Middle East/Africa markets, while smaller in aggregate scale, offer targeted opportunities tied to specific institutional modernization initiatives and regional distribution partnerships.
Our research integrates these regional realities into a cohesive operational view. We examine how supply routes, import dependencies, domestic manufacturing capacity, and local service networks influence delivery reliability and post-installation support. For enterprises managing multi-site deployments or evaluating cross-border procurement, these insights help reduce friction in forecasting, inventory planning, and vendor selection.
Competitive Profiles That Matter for Strategic Sourcing
The competitive field includes manufacturers with distinct positioning strategies, ranging from education-focused product lines to broad commercial and healthcare portfolios. Several players have built recognition around specialized surface treatments, magnetic functionality, frameless designs, and freestanding configurations tailored to specific user environments. Others emphasize custom fabrication, long-duration warranties, or region-specific distribution models that strengthen their relevance in institutional procurement cycles.
Our report profiles leading participants and examines how their product architectures, branding approaches, and manufacturing commitments translate into market relevance. We assess how companies differentiate through write performance, surface durability, mobility options, and presentation integration features, and how these attributes resonate with education administrators, office facility managers, and healthcare procurement teams. The analysis also considers how warranty structures and domestic production claims influence buyer confidence, particularly in environments where long service life and low maintenance burden are prioritized over initial acquisition cost.
Traditional Whiteboard Market
What the Report Delivers: Operational Intelligence, Not Just Market Sizing
This research is designed to support concrete decision-making across multiple organizational functions. It goes beyond headline figures to provide an actionable structure that procurement teams, strategy planners, and facility leaders can apply directly to planning processes.
- Historical performance context from 2020 through 2025, establishing a clear baseline for interpreting near-term revenue movement and demand stability
- Forward-looking projections through 2032 that map expected market progression under baseline conditions, helping organizations align capital planning with realistic growth expectations
- Material and application segmentation analysis that clarifies where specification differences matter most and how end-use environments drive purchasing behavior
- Competitive landscape mapping that identifies concentration patterns, differentiation pathways, and supplier evaluation criteria relevant to enterprise procurement
- Regional demand framing that supports multi-market planning without reducing complex local dynamics to oversimplified rankings
- Operational context drawn from manufacturing activity, supply responses, and end-user behavior trends that illuminate how the market functions in practice
The study is structured to help readers answer practical questions: Which product attributes justify premium specification in high-use environments? How do replacement cycles differ across education, office, and healthcare settings? What supplier characteristics should be weighted most heavily in multi-site procurement programs? By addressing these questions within a consistent analytical framework, the report enables more disciplined planning and reduces reliance on anecdotal procurement assumptions.
Using This Intelligence to Strengthen 2026 Decision-Making
Strategic value emerges when market data is connected to operational realities. In the Traditional Whiteboard Market, that connection is especially important because purchases are often distributed across departments, budget cycles, and facility teams. A classroom replacement program, a corporate office refresh initiative, or a healthcare wing renovation may all involve whiteboard procurement, but each operates under different specification priorities, approval pathways, and usage expectations.
Our research helps unify these perspectives by showing how demand patterns, product characteristics, and competitive dynamics intersect in practice. Procurement leaders can use the findings to benchmark sourcing criteria, evaluate supplier proposals against market-consistent specifications, and anticipate how replacement and expansion needs may evolve over the forecast period. Strategy and operations teams can incorporate the market trajectory into broader workplace planning, ensuring that physical collaboration infrastructure is treated as a deliberate component of organizational design rather than an incidental facility expense.
For organizations considering supplier diversification, regional sourcing adjustments, or specification standardization across sites, the report provides the context needed to weigh trade-offs with greater confidence. It also supports scenario thinking by clarifying which market segments are structurally larger, which material categories align with particular operating conditions, and how competitive concentration shapes negotiation leverage and supply continuity considerations.
Access the Full Market Intelligence
This overview is intended to demonstrate the scope, rigor, and strategic relevance of the full study. The complete Traditional Whiteboard Market research contains the detailed segmentation analysis, competitive profiling, regional demand mapping, and forecast structures that enterprise decision-makers require for 2026 planning and beyond. Core data tables, segment-level breakdowns, company-specific strategic assessments, and operational context are developed in full within the report to support procurement modeling, facility planning, and market positioning exercises.
To access the complete dataset and apply these insights directly to your organization's planning processes, visit the source page for the full report. The detailed intelligence inside is structured to be immediately useful for strategy reviews, budget forecasting, supplier evaluations, and multi-site operational planning throughout the 2026–2032 forecast period.
For detailed analysis of this topic, please visit the official page: Traditional Whiteboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CRO Market Projected to Reach USD 152.6 Billion by 2032, Growing at 8.85% CAGR
By PW Consulting, 2026-09-16
Navigating the CRO Landscape: Strategic Intelligence for 2026 Decision-Makers
The global pharmaceutical and biotechnology sectors are entering a period of profound transformation. As research and development pipelines grow more complex, biopharma sponsors are increasingly relying on Contract Research Organizations to manage clinical execution, regulatory navigation, and data-driven trial optimization. PW Consulting's latest CRO Market study delivers a comprehensive, forward-looking assessment of this ecosystem, providing executives with the analytical rigor required to make informed capital allocation, partnership, and operational decisions in 2026 and beyond.
This report is designed not as a static snapshot, but as a strategic navigation tool. It synthesizes historical performance across 2020 through 2025 with a detailed forecast horizon extending to 2032. By mapping growth trajectories, competitive pressures, and structural shifts in service delivery, the study equips leadership teams with the contextual intelligence needed to anticipate market movements rather than simply react to them.
Macro Market Trajectory: Growth Foundations and Forward Outlook
The CRO sector has demonstrated consistent expansion over the past half-decade, evolving from a supportive outsourcing function into a core strategic infrastructure for drug development. Historical data reveals a sector that has repeatedly absorbed volume increases, therapeutic complexity, and regulatory evolution while maintaining secular growth. From a baseline perspective anchored in 2025, the market has already crossed significant valuation thresholds, reflecting sustained sponsor demand for integrated development capabilities, specialized laboratory services, and accelerated trial delivery models.
Contract Research Organization (CRO) Market
Looking toward the forecast window of 2026 through 2032, the market is projected to continue its upward trajectory at a compound annual growth rate of 8.85 percent. This expansion is not uniform across all phases or segments; rather, it reflects selective acceleration in high-complexity areas, sustained demand for late-stage execution, and growing reliance on analytical and data-management services that reduce development risk. The forecast period captures a critical inflection point where operational efficiency, digital trial capabilities, and regulatory alignment become decisive competitive differentiators.
Revenue projections through 2032 illustrate a market that scales materially beyond current levels, reinforcing the strategic importance of early positioning. Organizations that understand where growth concentrates, which service lines command premium value, and how competitive dynamics shift over the forecast horizon will be better positioned to negotiate partnerships, structure internal capabilities, and capture margin resilience in an increasingly contested environment.
Core Dimensions of Market Composition
A clear understanding of how the CRO market is structured is essential for strategic planning. The study examines the industry through multiple analytical lenses, each illuminating a different facet of demand, competition, and value creation.
- By service model, the landscape spans clinical research execution, early phase development, laboratory and diagnostic support, and consulting-oriented engagement. Each category carries distinct operating economics, client retention dynamics, and scalability profiles that influence how sponsors select partners and how providers differentiate their offerings.
- By therapeutic focus, demand patterns reflect the scientific and regulatory demands of specific disease areas. Oncology, infectious disease programs, cardiovascular studies, and neurology and related indications each present unique trial design requirements, patient recruitment challenges, and data-generation expectations that shape service utilization and pricing dynamics.
- By geography, regional demand reflects variations in sponsor density, regulatory maturity, trial infrastructure, and cost structures. The study maps where development activity is concentrated, how execution capabilities are distributed, and what this implies for near-term capacity constraints and long-term market entry strategies.
These structural dimensions are examined not in isolation but in combination, allowing decision-makers to see how service demand, therapeutic complexity, and regional dynamics interact to create pockets of opportunity and pressure. Rather than presenting fragmented percentages in isolation, the report integrates these elements into a coherent view of where value is created and where competitive intensity is most acute.
Competitive Landscape: Concentration, Capabilities, and Strategic Positioning
The CRO market is characterized by a meaningful degree of concentration among established full-service and integrated providers, while simultaneously accommodating a diverse set of specialized and regionally focused operators. The study's competitive analysis evaluates how scale, scientific depth, data infrastructure, and therapeutic expertise influence market share, client relationships, and expansion pathways.
Market Concentration and Structural Implications
Concentration metrics indicate that a relatively small group of large providers commands a substantial share of aggregated industry revenue, reflecting the advantages of integrated service portfolios, global trial networks, and established sponsor relationships. At the same time, the remaining market is distributed across mid-tier and specialized firms that compete on speed, therapeutic specialization, regional access, or differentiated scientific capabilities. This dual structure matters for strategy: large providers often compete on breadth and risk-sharing, while smaller and mid-sized firms frequently win on agility, niche scientific expertise, and targeted regional execution.
Key Players and Strategic Profiles
The report profiles a broad set of organizations whose strategies define the current competitive environment. These include full-service clinical development organizations, integrated laboratory and imaging-enabled providers, firms combining trial execution with commercial launch support, and players with strong discovery-to-development or manufacturing-linked capabilities. The profiles assess operating models, service breadth, geographic reach, and the strategic logic behind recent moves in partnerships, acquisitions, and technology integration.
Among the firms analyzed are organizations headquartered across North America, Europe, and Asia-Pacific, reflecting the globalized nature of modern drug development. Their differing emphases illustrate the range of competitive approaches in the market: some prioritize end-to-end clinical delivery and analytics-driven trial management, others emphasize late-stage and government-sponsored research, while still others build value around integrated laboratory services, safety assessment, regulatory solutions, or combined development and manufacturing capabilities. Understanding these strategic orientations helps sponsors and investors evaluate fit, risk, and long-term positioning.
Recent Strategic Moves Shaping the Field
Competitive dynamics are also being reshaped by a series of notable developments that signal where the industry is placing its bets. In late 2025, one major full-service provider was recognized for excellence in clinical development, underscoring the continued premium on execution quality and sponsor trust. Around the same period, a leading laboratory and clinical services organization acquired a digital trial data and management platform for a substantial enterprise value, signaling the strategic importance of data infrastructure, decentralized trial capabilities, and technology-enabled operations.
In parallel, long-term clinical and commercial partnerships between major research organizations and platform technology providers have reinforced the trend toward deeper integration between trial execution and digital ecosystems. Collaborative initiatives involving artificial intelligence have also emerged, aimed at accelerating clinical development workflows, improving data quality, and reducing cycle times. Collectively, these moves highlight an industry in which technology, data, and partnership architecture are becoming as strategically important as traditional scientific and operational capabilities.
Market Dynamics: Technology, Regulation, and Operational Evolution
The CRO sector does not expand in a vacuum. Its trajectory is shaped by intersecting forces that influence how trials are designed, executed, and evaluated. Three dynamics are especially salient for 2026 planning.
Rare Disease CRO Service Market
Technology-Enabled Trial Execution
Digital tools, advanced data management, and AI-assisted workflows are increasingly central to clinical development. Sponsors are seeking partners that can integrate real-world evidence, analytics-driven trial management, and streamlined data capture into the development process. This shift is changing evaluation criteria for service providers, with capability in data integration, operational visibility, and adaptive trial support becoming key differentiators. The market study examines how these technology-oriented demands are influencing service mix, investment priorities, and competitive advantage.
Regulatory Standards and Evaluation Frameworks
Regulatory expectations and consensus standards continue to shape development strategies, particularly for organizations navigating early feasibility, device-related evaluations, and complex clinical assessments. Standards-developing bodies and consensus-standards adoption processes play a pivotal role in defining the quality, risk management, preclinical, and clinical evaluation expectations that sponsors and service providers must meet. Familiarity with these frameworks significantly influences regulatory strategy, especially in early-stage programs where alignment with recognized standards can reduce uncertainty and accelerate progression.
The report contextualizes these regulatory dynamics without treating them as isolated compliance issues. Instead, it frames them as structural drivers of demand for specialized expertise, quality systems, and regulatory-aware trial design. For CROs and sponsors alike, the ability to operate confidently within evolving standards environments is becoming a core strategic capability rather than a back-office function.
Service Integration and Value-Chain Positioning
A broader trend toward integration is evident across the market. Sponsors increasingly prefer partners that can connect clinical execution, laboratory support, imaging, data management, and regulatory consulting within a coherent delivery model. This preference is pushing providers to expand their value-chain footprint, whether through organic build-out, targeted acquisitions, or strategic alliances. The study analyzes how integration affects pricing power, client retention, operational risk, and the ability to support complex programs from early development through later-stage execution.
What the Study Delivers: Operational Content for Decision-Makers
This CRO Market study is built for practical use. Beyond high-level market sizing and growth trajectories, it provides decision-makers with structured analysis that can be applied directly to strategy, sourcing, investment, and competitive planning.
- A forecast-backed view of market evolution from 2026 through 2032, anchored in historical performance from 2020 to 2025, enabling scenario-aware planning rather than single-point estimates.
- Segment-level analysis across service categories, therapeutic areas, and geographic demand patterns, integrated to reveal where growth is most durable and where competitive intensity is rising.
- Detailed competitive profiling of leading and emerging providers, with attention to operating models, capabilities, and the strategic rationale behind recent partnerships, acquisitions, and technology initiatives.
- Assessment of the structural forces shaping the market, including digital trial infrastructure, regulatory-standard alignment, and value-chain integration, framed in terms of their implications for sourcing strategy and long-term positioning.
- Contextual intelligence on the operating environment, including the role of consensus standards and regulatory-review practices in influencing clinical evaluation pathways and early feasibility strategies.
Each section is designed to support concrete decisions: which partners align with a given development strategy, where capacity and expertise are likely to tighten, how service mix may shift as programs become more complex, and which competitive moves are likely to reshape sourcing options over the forecast period.
Strategic Implications for 2026 and Beyond
For executives planning in 2026, the central takeaway is that the CRO market is growing, but growth alone does not guarantee advantage. The real strategic question is how to align internal development ambitions with an external service environment that is becoming more concentrated at the top, more differentiated in the middle, and more technology-dependent across the board.
Organizations that approach CRO engagement strategically, rather than transactionally, will be best placed to manage risk and accelerate delivery. That means evaluating partners not only on cost and timeline, but also on data infrastructure, regulatory fluency, therapeutic depth, and the ability to support integrated development pathways. It also means recognizing that recent industry moves around digital trial capabilities, AI-enabled workflows, and major platform acquisitions are not isolated headlines; they are indicators of where competitive advantage is being built.
Likewise, sponsors and investors should pay close attention to concentration trends and the strategic behavior of leading providers. A market in which a limited number of large firms command a substantial share of revenue will reward early relationship-building, clear capability requirements, and disciplined evaluation of long-term partnership options. At the same time, specialized and regionally oriented providers will continue to offer important alternatives for programs that demand focused expertise or specific geographic access.
Conclusion: From Market Intelligence to Actionable Strategy
The CRO sector is entering a phase in which scale, scientific capability, technological integration, and regulatory alignment converge to define competitive success. PW Consulting's CRO Market study provides the analytical foundation needed to navigate that convergence with confidence. By combining historical context, forecast-driven perspective, and competitive intelligence into a single strategic framework, the report helps executives move from awareness to action.
The full study contains the detailed segmentation analysis, company-specific evaluation, and forward-looking market logic required to translate these insights into concrete decisions for 2026 planning and beyond. For teams seeking a deeper, data-rich view of where the market is headed and how to position accordingly, the complete report offers the comprehensive intelligence necessary to support informed, strategically aligned action.
For detailed analysis of this topic, please visit the official page: Contract Research Organization (CRO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China High Voltage Battery Market is forecast to grow from an estimated $18,400 Million in 2025 to over $67,900 Million in 2035. This growth trajectory reflects strong demand in mobility, renewable integration, and industrial electrification sectors. Steady investment and scaling by established and emerging players, coupled with technology breakthroughs and policy support, are fueling a multi-year expansion. Year-on-year revenue is expected to see double-digit percentage growth, particularly in early forecast years as infrastructure and market adoption accelerate across China.
Read More - https://bussinessinsights.com/research-report/china-high-voltage-battery-market
Electric vehicles account for the majority share of high voltage battery applications in 2025, aligning with China’s leadership in global EV production and adoption. Hybrid vehicles and renewable energy storage also constitute significant portions of the market, reflecting policy-driven initiatives to decarbonize both transport and the energy sector. Grid storage and industrial equipment segments continue to benefit from demand for high-performance, scalable battery solutions. The future trajectory is expected to see even greater shares for renewable energy and grid storage as energy transition accelerates nationwide.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-high-voltage-battery-market
Frequently Asked Questions
Who are the key players in China High Voltage Battery Market industry?
The top five players in China's high voltage battery market are Contemporary Amperex Technology Co. Ltd. (CATL), BYD Company Limited, Gotion High-tech, CALB (China Aviation Lithium Battery), and EVE Energy. These companies dominate the industry through advanced technology, robust manufacturing capabilities, and supplying leading automotive OEMs.
What is the China High Voltage Battery Market growth?
China's high voltage battery market has witnessed remarkable growth in 2023, driven by surging electric vehicle sales. For instance, CATL reported a 23% year-on-year revenue growth due to rising demand for high-voltage batteries in electric cars and commercial vehicles, solidifying its market-leading position.
Which segment accounted for the largest China High Voltage Battery Market share?
The automotive application segment holds the largest share in China's high voltage battery market. Growing adoption of electric vehicles, particularly passenger cars and buses, by manufacturers such as BYD, has accelerated demand for high-performance batteries designed specifically for automotive propulsion.
Thanks & Regards,
priya
sales@bussinessinsights.com
Navigating the Next Wave: Strategic Intelligence for the Billet Casters Market Through 2032
The global billet casters market is entering a decisive phase of evolution. As steelmakers and aluminum producers balance capacity expansion with the imperative for higher metallurgical quality, the equipment that transforms molten metal into usable billets has become a critical leverage point in the value chain. PW Consulting's latest in-depth market research on the Billet Casters Market is designed to give executives, investors, and technology strategists the clarity required to navigate this landscape through 2032. This article previews the strategic architecture of the study, outlining how its data-driven framework, competitive mapping, and operational cost intelligence can be translated into actionable decisions in 2026 and beyond.
Why 2026 Demands a Reset in Equipment Strategy
Over the past half-decade, the market has transitioned from a post-pandemic recovery posture to a structurally recalibrated growth trajectory. Historical performance from 2020 through 2025 reveals a market that weathered supply chain disruptions, shifting demand cycles, and capital expenditure hesitancy, yet sustained a clear upward path. Building on that foundation, the forecast window extending to 2032 projects a compound annual growth rate of 5.5 percent, measured in USD millions. This trajectory is not merely a top-line exercise; it reflects the cumulative effect of modernizing legacy casting lines, integrating high-speed continuous casting machines, and addressing the rising demand for precision-defined billets in advanced steel grades and non-ferrous applications.
For decision-makers evaluating capital allocation in 2026, the strategic question is no longer whether the market is expanding, but where the margin for competitive advantage lies. Upgrading a single casting strand, selecting between vertical and horizontal configurations, or incorporating electromagnetic stirring and dynamic secondary cooling can reshape throughput, energy consumption, and scrap rates over the life of a plant. The research underlines that these are not isolated equipment purchases; they are strategic bets on future metallurgical performance, operational resilience, and total cost of ownership. A nuanced reading of market momentum, paired with granular technology and cost benchmarks, helps executives prioritize investments that compound value rather than simply adding capacity.
What the Research Delivers: Content Built for Execution
This study is structured to move beyond descriptive market size and into the operational and commercial territory that influences real budgets and timelines. It opens with a rigorous reconstruction of historical demand through 2025, establishing a defensible baseline against which the 2032 outlook can be stress-tested. From there, the analysis extends into forward-looking scenarios that account for plant modernization cycles, regional capacity additions, and the interplay between product type adoption and end-use requirements.
The report also dissects the economics that shape purchasing decisions. Equipment valuation is influenced not only by the caster itself but by the surrounding ecosystem of design, fabrication, integration, and commissioning. Precision machining, welding, and hydraulic system integration represent a significant share of project value, while research and development together with certification activities add further layers of cost and risk. High-grade alloy steels, refractory materials, and copper for mold tubes and specialized components account for a substantial portion of the total caster cost. On the infrastructure side, greenfield installations encompassing civil engineering and ancillary equipment can reach or exceed fifty million dollars. These cost structures matter because they determine the financial logic behind renovation versus replacement, and because they vary meaningfully across segments, geographies, and machine specifications.
Beyond costs, the study connects technical choices to regulatory and standards-driven realities. Billet casters operating in today's environment must satisfy metallurgical industry standards and safety certifications, particularly when processing high-alloy grades and ultra-large sections approaching diameters of 1000 mm. The research translates these compliance requirements into procurement implications, illustrating how specification rigor, testing protocols, and documentation expectations influence vendor selection, project timelines, and long-term service obligations.
Casters Market
Competitive Landscape and Recent Moves That Matter
The market exhibits a consolidated structure, with the top three participants collectively holding a substantial share and the top five extending that footprint further. This concentration creates a landscape where technology leadership, service networks, and localized execution capabilities are often as important as headline pricing. The research profiles the core companies shaping this environment, examining their engineering philosophies, product families, and go-to-market positioning.
Among the leaders, SMS group GmbH continues to advance its Concast division's custom billet caster offerings, spanning vertical and curved designs with strand configurations from one to ten and casting speeds up to seven meters per minute. Danieli & C. Officine Meccaniche S.p.A. positions its Q-CAST billet casters with POWER MOULD and HY-POWER oscillation systems as a route to higher productivity and billet and bloom quality across varied steel market requirements. Primetals Technologies Limited, through its wholly owned subsidiary Concast India Private Ltd., emphasizes modular casters for mini-mills with a focus on square and rectangular sections and high-speed rebar integration, while Electrotherm E&T Ltd. addresses smaller heat sizes down to five tons with compact, modular designs suited to existing ingot-to-billet conversion scenarios. Concast India Private Ltd. extends this modular logic with five- to seven-strand configurations tailored for steel billet production in mini-mill environments.
What distinguishes the current period is the cadence of live project activity. In October 2025, Danieli & C. Officine Meccaniche S.p.A. secured a contract for a new three-strand continuous casting machine designed to produce ultra-large high-alloy round billets up to 1000 mm in diameter, including specialized grades such as P91 and P92. In January 2026, SMS group GmbH was awarded a modernization contract for an eight-strand continuous caster at a second plant location, with Dynamic Mechanical Soft Reduction intended to improve billet inner quality. Earlier in July 2025, Concast India Private Ltd. received an order for a new billet caster handling 100- to 200-mm square sections, integrated with a high-speed rebar outlet. In April 2025, Danieli's service team completed an upgrade of a six-strand billet caster in Italy, reinforcing the recurring value of modernization alongside new capacity.
These developments are not isolated headlines; they are signals. They reveal where premium specifications are being demanded, how service-led upgrade cycles are being monetized, and why integration with downstream outlet configurations is increasingly part of the value proposition. The study maps these patterns to competitive behavior, highlighting where incumbents defend share through advanced casting technologies and where challengers compete on modularity, footprint, and integration with smaller melt shops.
Dynamics Shaping Investment Logic in 2026
Several intersecting dynamics will determine how aggressively capital is deployed and how equipment specifications are negotiated. Energy efficiency has emerged as a decisive differentiator for high-end multi-strand machines. Advanced casters equipped with electromagnetic stirring, dynamic secondary cooling, and heightened automation command a premium price range between 15 million and 45 million dollars per machine. The business case for such specifications depends on the balance between throughput gains, metallurgical consistency, and operating cost reduction over the machine's service life.
At the same time, total project economics must account for more than the equipment invoice. Greenfield installations require civil engineering, utilities interfaces, and ancillary equipment, pushing aggregate spend to fifty million dollars or more in certain configurations. For organizations operating in brownfield contexts, the calculus shifts toward footprint compatibility, retrofit complexity, and the ability to sustain production continuity during installation and commissioning. The research helps decision-makers compare these pathways using consistent cost and capability benchmarks rather than ad hoc quotations.
Billet Casters Market
Another important dynamic is the tightening relationship between product specifications and downstream performance. As producers target higher-alloy steels and increasingly demanding non-ferrous billets, the tolerance for internal defects, centerline segregation, and surface quality issues narrows. This raises the strategic importance of casting speed control, mold design, oscillation systems, and cooling precision. The report connects these technical levers to segment-level demand signals and to the competitive responses of equipment suppliers, enabling procurement teams to evaluate proposals against a clearer standard of operational readiness.
Strategic Applications for 2026 Decision-Making
This research is intended to be used, not merely read. For capital planning teams, it provides a structured basis to align budget cycles with realistic equipment lead times, installation complexity, and the cost architecture of competing solutions. For technology and procurement leaders, it offers a way to benchmark vendor claims on oscillation systems, mold technology, strand configuration, and downstream integration against the broader market's observed direction. For strategy and corporate development functions, the study clarifies where concentration creates bargaining power and where niche configurations can serve as differentiators in specialized applications.
- Prioritize investment pathways that balance immediate capacity needs with long-term quality and energy performance, using the forecast period to test multiple upgrade and expansion scenarios.
- Evaluate proposals against consistent cost and specification baselines that include machining, welding, hydraulic integration, R&D, certification, and ancillary infrastructure rather than comparing machine prices in isolation.
- Align procurement with regulatory and standards expectations for high-alloy grades and ultra-large sections, ensuring that compliance requirements are factored into vendor selection and project scheduling.
- Use competitive intelligence to anticipate where incumbents will defend share through advanced casting technologies and where modular, smaller-footprint solutions can open opportunities in mini-mills and conversion projects.
- Incorporate recent project activity into scenario planning, recognizing that large-diameter high-alloy billets and dynamic soft reduction upgrades reflect shifting performance priorities that may influence future specification trends.
Where to Focus Next
The full scope of this research extends into more detailed comparative frameworks, scenario analyses, and operational benchmarks that are essential for precise budgeting and vendor evaluation. Because competitive dynamics, cost structures, and specification trends vary meaningfully across segments and project types, the most valuable intelligence resides in the granular layers of the study rather than in the headline totals alone. Readers seeking to translate market momentum into concrete capital decisions will find the complete report most useful when paired with internal plant data, project timelines, and specification roadmaps.
The market for billet casters is no longer defined by volume growth alone. It is being reshaped by quality demands, energy economics, compliance rigor, and the pace of technological differentiation among leading suppliers. PW Consulting's Billet Casters Market research is built to help organizations read these signals correctly and act on them with confidence. For executives preparing 2026 decisions and beyond, the study offers a disciplined way to connect market direction to equipment strategy, cost logic, and competitive positioning. The next step is to examine the detailed intelligence that underpins this outlook and to apply it within the specific constraints and ambitions of each organization's operating environment.
For detailed analysis of this topic, please visit the official page: Billet Casters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China IoT Technology Market is set for considerable expansion, with revenue anticipated to rise from $34,000 Million in 2020 to $215,000 Million by 2035. This surge reflects a CAGR above 13% from the base year 2025 to 2035. Widespread deployment across industries, strengthened by 5G proliferation and strategic investments from leading tech giants, drives this robust growth. Particularly strong performance is expected in industrial, healthcare, and urban infrastructure applications. The trajectory underlines China’s ambitious technology agenda, with continuous innovation spurring adoption and market penetration.
Read More - https://bussinessinsights.com/research-report/china-iot-technology-market
Smart manufacturing is projected to take the lead in 2025 with a 32% share, emphasizing China’s focus on industrial automation and intelligent production lines. Smart healthcare and smart transportation follow closely at 22% and 18%, respectively, driven by advancements in telemedicine and connected logistics. Other growing segments include smart energy (12%), smart retail (9%), and smart agriculture (7%). This approach highlights China’s strategic priorities in leveraging IoT for industrial efficiency, public welfare, and rural revitalization. Accelerated digitalization in healthcare and transportation further solidifies their positions as high-impact, rapidly growing segments.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-iot-technology-market
Frequently Asked Questions
Who are the key players in China IoT Technology Market industry?
The top 5 players are Huawei, Alibaba Cloud, China Mobile, Xiaomi, and ZTE. Huawei leads with comprehensive IoT infrastructure; Alibaba Cloud empowers digital transformation; China Mobile dominates IoT connectivity; Xiaomi integrates IoT into smart devices for consumers; and ZTE focuses on end-to-end IoT solutions for various industries.
What is the China IoT Technology Market growth?
The China IoT Technology Market is experiencing robust double-digit growth, primarily due to aggressive network expansion by companies like China Mobile. The adoption of 5G IoT solutions and smart city initiatives in 2023 significantly accelerated market growth, positioning China as the global IoT market leader.
Which segment accounted for the largest China IoT Technology Market share?
Smart home applications held the largest market share in China in 2023. This segment benefits from rising consumer demand for connected devices, home automation, and security solutions, with companies like Xiaomi and Huawei leading in innovative smart home products and ecosystem integration.
Thanks & Regards,
priya
sales@bussinessinsights.com